

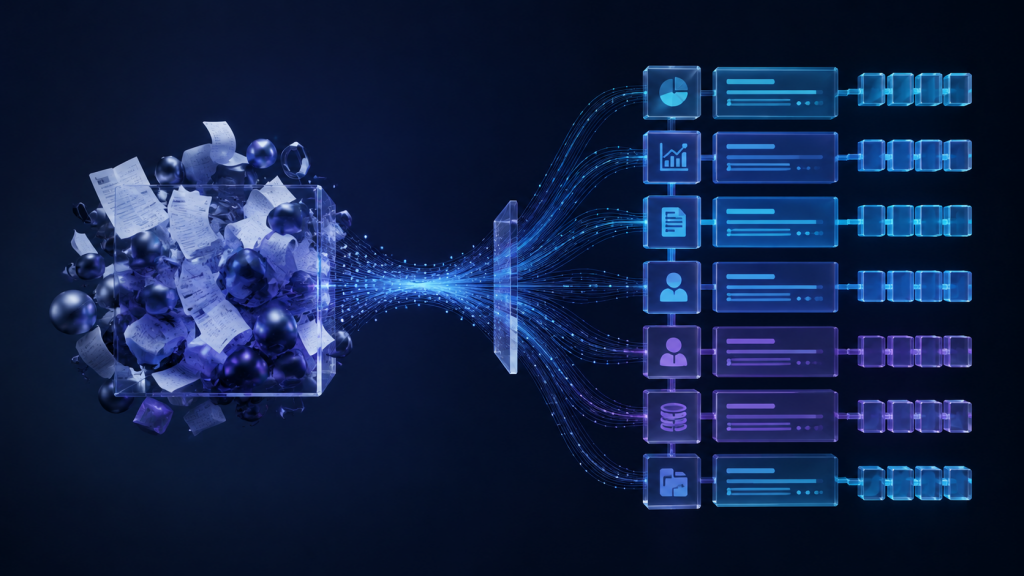
“Other income”, “other expenses” and “other items” are common in charts of accounts and financial reports. IFRS 18 strengthens the principles of aggregation and disaggregation and requires groups to reconsider whether these groupings remain appropriate.
IFRS 18 does not literally prohibit the word “other”
The standard does not ban every “other” label. It does require that material information not be obscured by excessive aggregation or insufficiently descriptive labels. A residual item must remain understandable and its composition must be explainable.
Why current data may be insufficient
When a group account receives very different transactions, the breakdown is often produced manually when preparing the notes. This becomes risky if details are no longer available or materiality thresholds are assessed too late.
Consequences for granularity
- create better-defined accounts or subaccounts;
- add analytical dimensions;
- collect additional details in reporting packages;
- retain transaction-level detail;
- introduce materiality controls and alerts on residual items;
- ensure consistent labels between primary statements and notes.
Avoid two opposite extremes
Insufficient granularity hides useful information, while excessive granularity overloads data collection and complicates controls. The right level depends on the nature, similarity and materiality of items and the needs of financial statement users.
Impact on EPM systems
Tools must support drill-down from a published item to its components. Grouping rules must be transparent and “other” items monitored automatically. An alert can be triggered when a balance exceeds a threshold or contains a material component.
A practical approach
- inventory lines and accounts containing “other”;
- analyze their composition over several periods;
- identify recurring or material components;
- define the required breakdowns;
- adapt the chart of accounts, forms and controls;
- harmonize labels in all publication languages.
A benefit beyond IFRS 18
Greater granularity also improves management control, variance analysis and forecast quality. Data collected for IFRS 18 can therefore become a management asset, provided it does not become a purely regulatory exercise disconnected from internal use.
The goal is not to multiply accounts, but to have the useful detail in the right place and at the right time, with clear governance.